Market Note · Rates
Treasury supply is rising. Who gets paid to absorb it?
Coupon issuance keeps rising through 2026. We estimate how much term premium buyers now demand and what it means for duration and curve positioning.
Key takeaways
- Net issuance of Treasury notes and bonds is set to rise for a sixth consecutive quarter, and a growing share is landing at maturities of seven years and longer.
- Our estimate of the 10-year term premium has risen by roughly 45 basis points since early 2025. We expect a further 10 to 15 basis points if long-end auction sizes increase again.
- We prefer to hold duration in the 5-year sector rather than the 30-year, and we use a 10s/30s curve steepener as a partial hedge against supply-driven weakness at the long end.
What changed this quarter
The U.S. Treasury finances deficits with a mix of bills, which mature within a year, and coupon securities: notes and bonds. Through 2024 and much of 2025 the Treasury leaned on bills and kept coupon auction sizes broadly stable. That has changed. Recent quarterly refunding announcements have raised auction sizes across the 2- to 30-year sectors, and the Treasury’s borrowing estimates point to further increases through the end of 2026.
The mix matters as much as the total. Bills are bought largely by money market funds, which treat them as cash and are relatively indifferent to the price of duration. Coupon securities must be absorbed by investors who take on interest rate risk: pension plans, insurers, banks, foreign official holders, bond funds and leveraged investors. Each of those groups has to be paid to hold more duration, and that payment is the term premium.
Why supply shows up in the term premium
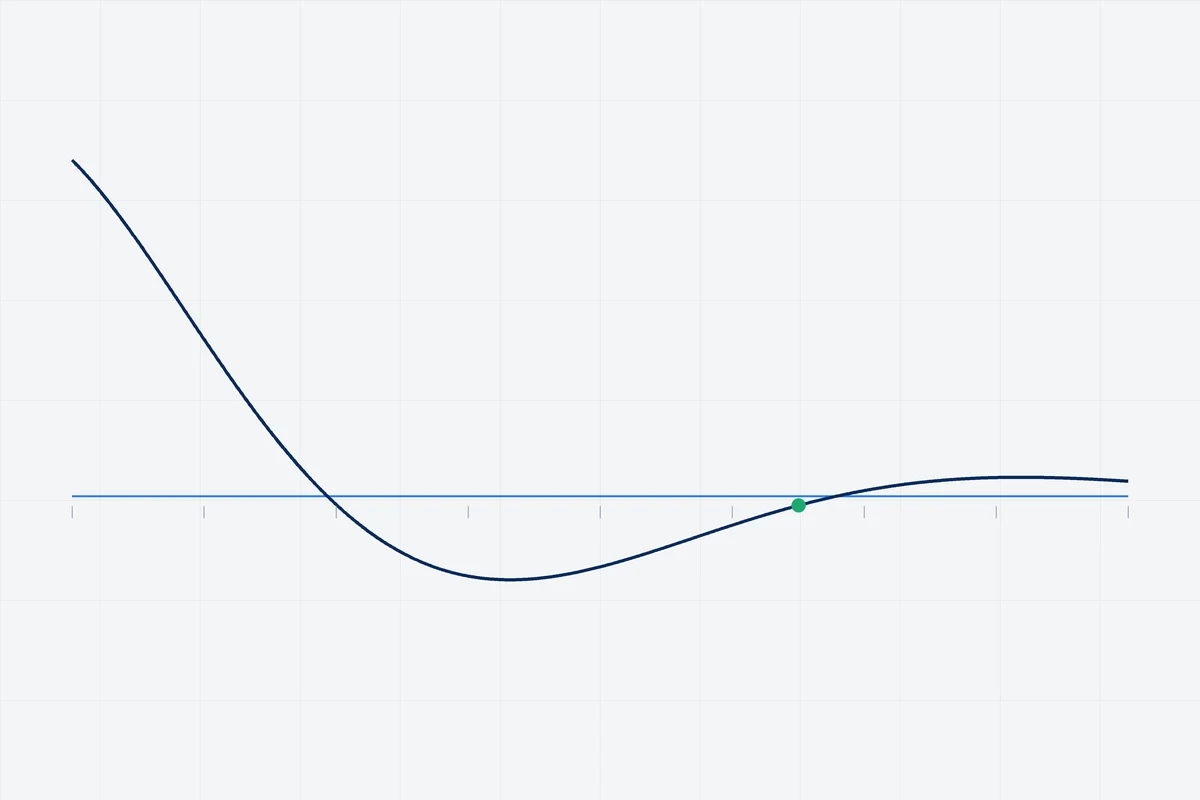
The yield on a 10-year Treasury can be split into two parts: the average short-term policy rate investors expect over the next ten years, and an extra yield for locking money up for that long instead of rolling short-term bills. The second part, the term premium, cannot be observed directly. It is estimated with models that compare yields with surveys and forecasts of future policy rates, and different models can disagree by 50 basis points or more on its level. We pay more attention to changes than to levels, and to the direction on which several models agree.
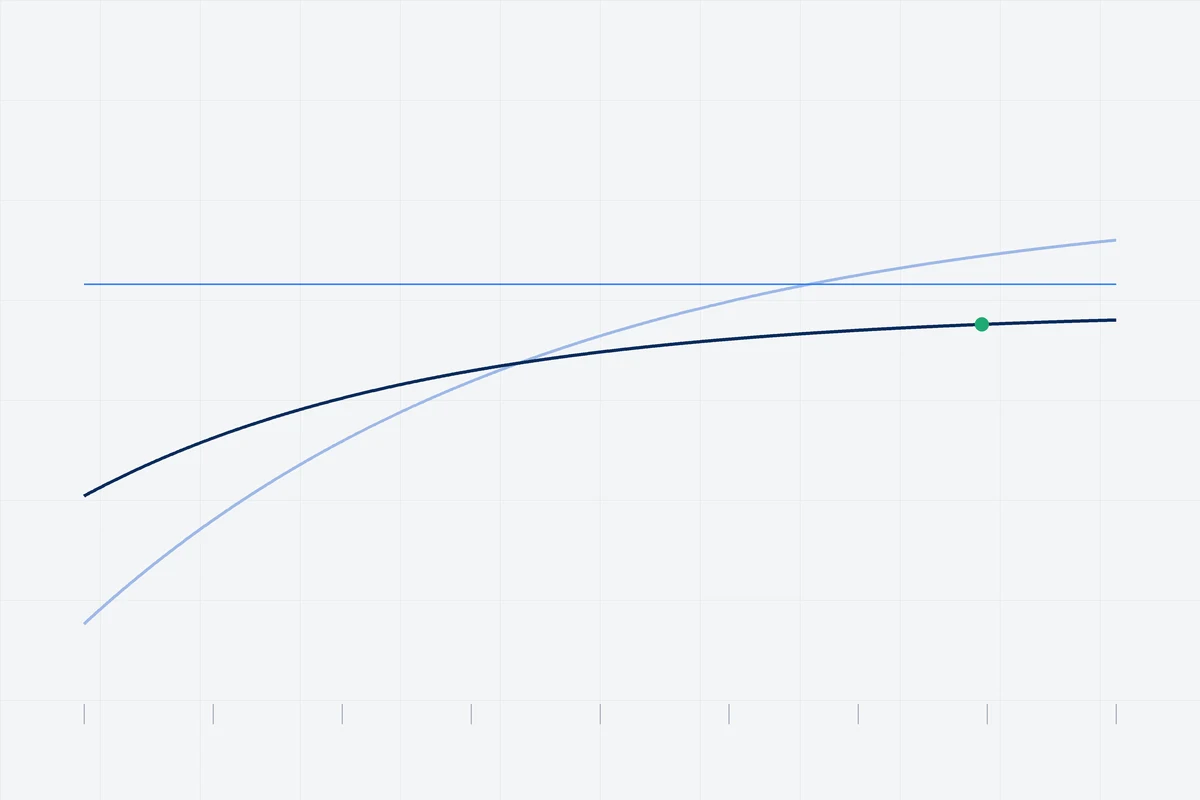
Supply reaches the term premium through the balance sheets of marginal buyers. With the Federal Reserve no longer adding to its holdings and foreign official demand broadly flat, more duration has to be held by price-sensitive investors. Those investors set prices at the margin, and they ask for more yield when asked to hold more risk. In our estimate, the 10-year term premium moved from about 20 basis points in early 2025 to close to 70 basis points in the second quarter of 2026, with the largest increases arriving around refunding announcements that raised long-end auction sizes.
Not all of that rise is supply. Uncertainty about inflation and the path of policy has also increased, and investors want compensation for that too. Our working assumption is that about half of the increase since early 2025 reflects supply and the balance-sheet capacity of buyers, and the rest reflects inflation and policy uncertainty. That split is an estimate, not a measurement, and we revise it as evidence arrives.
Who is buying, and at what price
We track demand at auction with three measures: the bid-to-cover ratio; the share awarded to indirect bidders, a rough proxy for foreign and institutional demand; and the “tail,” the gap between the auction’s clearing yield and the yield trading just before the auction. A tail of more than one basis point means the Treasury had to pay up to place the issue.
Through the first half of 2026, demand at 2- and 5-year auctions has been steady, supported by expectations that the Federal Reserve will lower rates over the next year. Investors who expect lower policy rates are happy to own shorter maturities. Demand at 20- and 30-year auctions has been softer, with tails at several recent long-bond auctions. That pattern fits buyers who are comfortable with policy-rate risk but reluctant to take on more term risk at the long end.
| Sector | Auction demand | Our valuation |
|---|---|---|
| 2-year | Strong; tails rare | Fairly valued |
| 5-year | Steady; tails rare | Modestly cheap |
| 10-year | Mixed | Fairly valued |
| 30-year | Soft; tails at several auctions | Rich relative to expected supply |
What it means for positioning
Three conclusions follow for portfolios in our Rates & Treasuries strategy:
- Hold duration where the buyers are. We keep duration exposure concentrated in the 5-year sector, where auction demand is steady and our fair-value model shows modest excess yield. We hold less in the 30-year sector, where new supply must be absorbed by a narrower group of buyers.
- Use the curve as a hedge. A position that gains if the gap between 10- and 30-year yields widens, a 10s/30s steepener, tends to benefit when supply pushes long-end yields higher. We size it as a partial hedge, not as a standalone bet.
- Watch the refunding calendar. The quarterly refunding announcement is the most important scheduled event for the term premium. We review positions in the week before each one and reduce long-end exposure if borrowing estimates surprise higher.
What would change our view
Two developments would lead us to take off the steepener and add back long-end duration. The first is a clear shift in issuance toward bills, which would ease pressure on coupon buyers. The second is a sustained improvement in long-bond auction demand, measured by smaller tails and a higher indirect share over three consecutive auctions. A sharp economic slowdown would also change the picture: expectations of lower policy rates would likely dominate, and long-end yields could fall even as supply rises.
Our quarterly view on duration and the curve is published in the Outlook series. We will update this note after the next refunding announcement; earlier work is collected under Rates.
This material reflects the views of the author as of the date of publication, is subject to change, and is provided for informational purposes only. It is not investment advice or a recommendation to buy or sell any security. Term premium estimates are model-based and differ across models; all figures shown are approximate. Forecasts are not guarantees. Investing involves risk, including possible loss of principal.